


The four ways stablecoins reach an equity portfolio
 9 min read
- Finance
- Altcoins
- Data
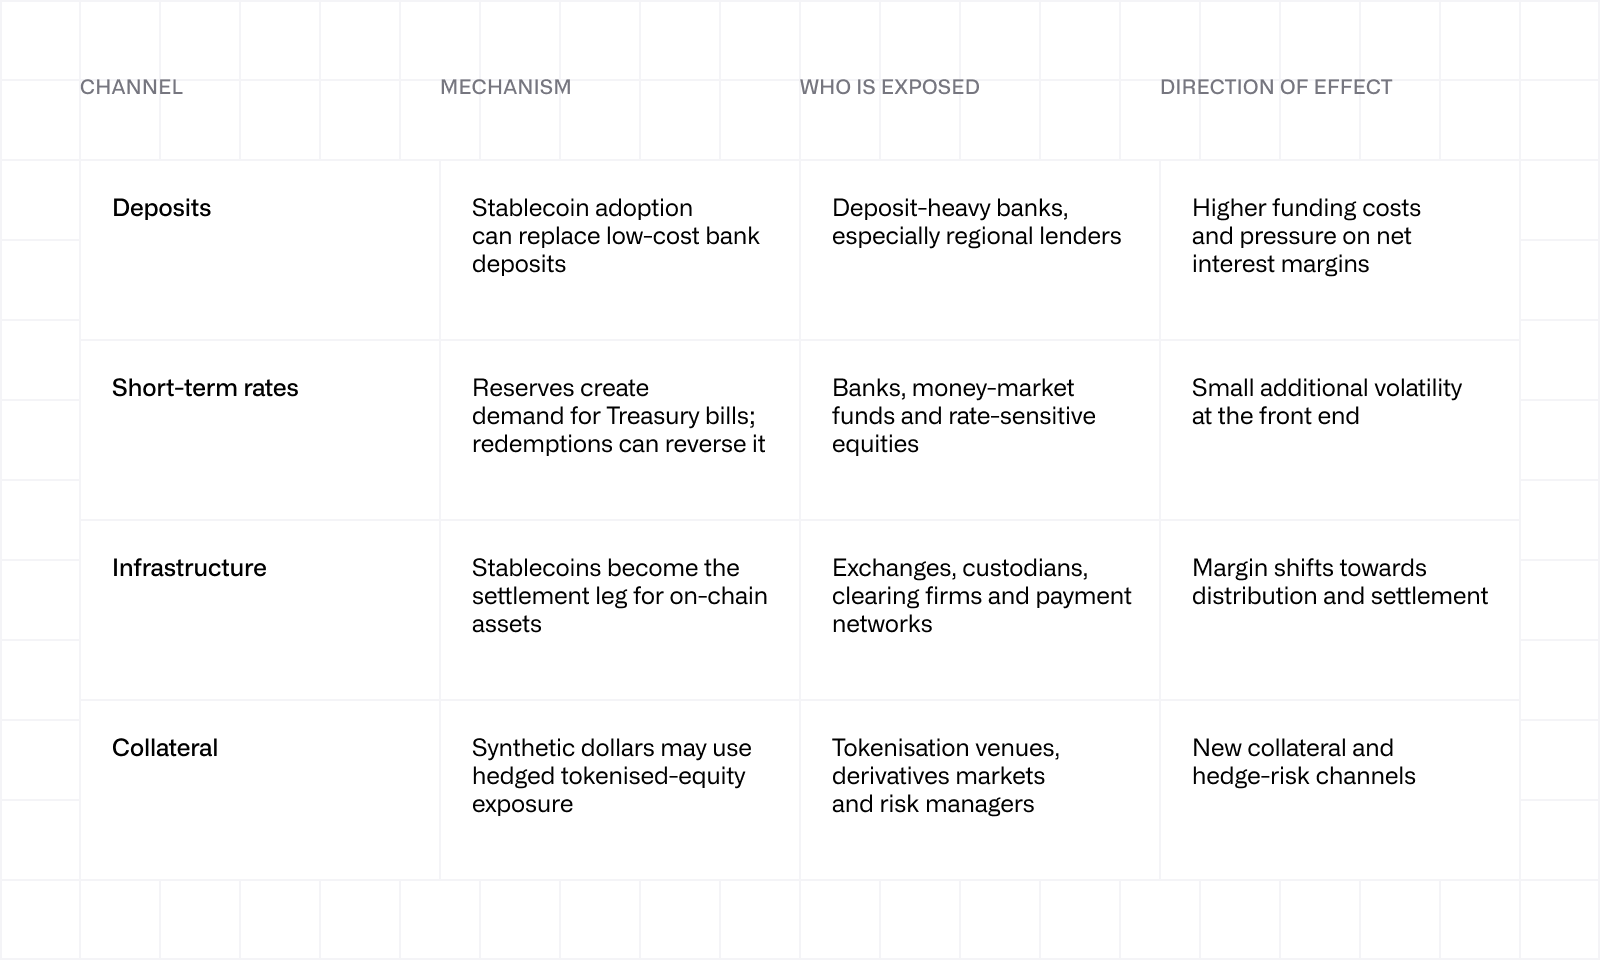
Stablecoins have grown beyond a crypto-market story. They can move the earnings and valuations of listed banks, exchanges and payment networks without an investor ever buying one. When people move cash from current accounts into tokens backed by Treasury bills, banks lose cheap funding and may have to replace it at a higher cost.
Do stablecoins take deposits away from banks, and which banks are most exposed?
Treasury advisers flagged $6.6T of US transactional deposits as exposed in April 2025 and total stablecoin supply equals 4.6% of that figure. An IMF study with data to June 2025 found no significant share price reaction in large or community banks to stablecoin demand shocks. So far, stablecoin adoption looks more like a margin risk than a funding shock.
A stablecoin works like a very simple bank. Someone hands over a dollar and the issuer keeps safe assets against it, known as stablecoin reserves. A current account is cheap, steady funding, because customers rarely move it and earn little for leaving it there. When that dollar moves into a stablecoin, the bank has to replace it with funding that costs more.
The scale so far is small next to the pool at stake. Total supply stood at $305.83B on 27 September 2026, 0.8% below the $308.16B of 31 March. Two issuers, Tether and Circle, hold 84.7% of it. A static market is itself the finding: the deposit threat is a question of years and policy, not of this quarter's growth rate.
Exposure is uneven. Investors can screen on net interest income as a share of total revenue: lending-heavy banks, such as US regional lenders, score higher than diversified banks or investment banks, so they have more to lose if funding costs rise. The same screen works on European financials.
The policy fight sets the speed. The GENIUS Act, signed in July 2025, requires one dollar of reserves for every token and bars issuers from paying interest to holders. It does not clearly stop exchanges paying rewards on tokens held on their platforms, and many do. According to the Congressional Research Service (6 March 2026) and the Council of Economic Advisers (April 2026), banks want exchanges to stop paying rewards on stablecoins, because those rewards make the tokens compete more directly with bank deposit accounts. Exchanges want to keep offering them. It is a fight over whether a token is allowed to look like a current account, with bank equities on one side and exchange equities on the other.
How do stablecoins affect Treasury bill yields and short-term rates?
Stablecoin reserves sit mostly in short-dated US government instruments, so supply growth adds demand at the front end. BIS research using data through March 2026 finds that a $3.5B inflow lowers three-month bill yields by 0.7 basis points on impact and about four basis points within ten days, with a larger effect when Treasury-market liquidity is strained.
A basis point is one hundredth of a percentage point, so the effect is real but small. An earlier version found that equal-sized outflows had a larger effect. The current BIS research does not restate that comparison, so treat the asymmetry as unsettled.
In its Q2 2026 attestation release of 31 July 2026, Tether reported $187.8B of total assets at 30 June, with most reserves held in US government-backed instruments and short-term liquidity facilities.
For an equity investor, growth is a mild tailwind for bill prices. A shrinking market could be a sharper shock, because the stress that triggers redemptions is when the bill market can least absorb the selling. The BIS paper measures the yield response to stablecoin flows; it does not show that redemptions occur when bill-market liquidity is weakest. Treat this as a risk scenario, not an observed outcome. Redemptions on that scale have not been tested. The largest seven-day fall in supply in the past year was $3.83B, in the week to 1 February 2026.
What an equity investor takes from this is not a level but a variance. Stablecoins add a little to rate swings and do not set the level, but short rates feed bank funding costs, money market fund yields and the discount rate on every other asset.
How are stablecoins changing settlement and market infrastructure?
Stablecoins are becoming the cash leg of on-chain settlement, so distribution and settlement revenue is now contested. Circle’s five-year agreement with Binance, announced on 22 September 2026 with a $100M Binance equity investment, shows how much issuers lean on large distributors for reach.
The settlement leg is the cash side of a trade, where money changes hands as the asset is delivered. On blockchains, that leg increasingly uses stablecoins. This is the most structural channel: its importance depends less on today’s supply growth than on where tokenised assets eventually settle. Where an asset settles, in which currency and on whose rails are revenue questions for exchanges, clearing houses, custodians and card networks, all of which are listed.
Two features of the plumbing matter. A dollar that settles in seconds, at any hour, can be posted, moved and recalled in ways a bank wire cannot, which lets intermediaries hold smaller buffers and changes what their service is worth. And because stablecoin settlement never closes while shares trade on exchange hours, a timing gap opens between the two markets.
Ethereum’s share of stablecoin supply fell from 53.0% to 48.0% between 31 March and 27 September 2026, while Tron rose from 28.0% to 30.9%, Solana from 4.8% to 5.4% and Hyperliquid from 1.7% to 2.5%. The shift indicates which networks are gaining a larger share of stablecoin liquidity and, with it, greater economic relevance.
Distribution is where the rent settles. Circle’s release describes a $100M share purchase by Binance at a 5.0% discount, and a commercial agreement under which Binance promotes USDC and Circle provides infrastructure. It gives no fee terms. With total supply broadly flat and USDC share little changed (24.7% against 25.1% on 31 March), the deal suggests distribution has become a cost of defending reach. Whether it reduces issuer margins depends on terms Circle has not yet disclosed. The question for investors is not whether stablecoins win but which listed layer keeps the margin.
Why are stablecoins starting to be backed by tokenised equities?
Ethena said on 25 September 2026 that Binance will be its first venue for extending USDe’s basis trade into equity perpetual futures, and The Block reported that part of the backing will be tokenised US equities. Equities are becoming collateral for instruments priced like cash, which makes the quality of that collateral a diligence question.
USDe is a synthetic dollar backed by a trade rather than bank deposits. Ethena holds tokenised equities, blockchain tokens that track listed shares, and shorts matching perpetual futures, derivatives without an expiry date, so price movements are designed to offset. The remaining return is the funding rate, a payment between traders for leverage. Cash-and-carry, in other words, with equities in place of commodities.
This creates a new source of demand for tokenised shares and equity perpetuals, driven by collateral needs rather than a view on the company. The key question is whether the hedge holds under stress, given that equity-perpetual markets are far thinner than their crypto equivalents. Synthetic dollars can blur the line between cash-like instruments and equity-backed collateral.
Ethena deserves a fair counterweight. USDe supply fell 74.7%, from $14.83B on 4 October 2025 to $3.75B on 28 April 2026, a redemption of that size settled without the instrument breaking, which is the test the design exists to pass. It stood at $4.94B on 27 September 2026.
The practical step is not to form a view on any stablecoin. It is to know where in a portfolio the exposure already sits: regional bank margins, front-end rate swings, exchange and payment network revenue, and now the collateral behind instruments treated as cash.
FAQs
Do stablecoins take deposits away from banks, and which banks are most exposed? Some deposits move, but supply is flat and equals 4.6% of the $6.6T of US transactional deposits flagged as at risk. Deposit-funded lenders, such as US regional banks, carry the most exposure.
How do stablecoins affect Treasury bill yields and short-term rates? Slightly: BIS research finds a $3.5B inflow lowers three-month bill yields by about 4 basis points within ten days.
How are stablecoins changing settlement and market infrastructure? Settlement and distribution revenue is now contested between exchanges, custodians, clearing firms, card networks and issuers.
Why are stablecoins starting to be backed by tokenised equities? Equity hedges widen the pool of assets that can back a synthetic dollar beyond crypto, at the cost of tying its stability to thinner equity derivatives markets.
Published onOct 23rd, 2026
